From Clay Tablets to Central Banks – From Babylon to Basel
 Every bank account rests on an old idea: that a promise written down can travel further than the coins it represents.
That idea begins in the temples of Babylon. It passes through the counting houses of Florence and Genoa, the exchanges of Bruges, Antwerp and Amsterdam, and arrives in London in 1694 with the founding of the Bank of England. From there it spreads to Washington, to Basel in Switzerland, and to the global institutions of today. At each stage, banking makes something new possible: wider trade, larger armies, overseas empires, and finally cooperation between nations.
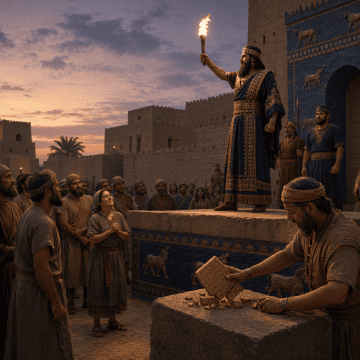
Babylon: the temple and the tablet
From around 3000 BC, the temples and palaces of Sumer kept accounts, collected rents and advanced goods to merchants. Grain and silver served as money, and by the end of the third millennium silver had become, in Michael Hudson’s phrase, the “money of the world”. Commercial loans in silver carried a standard rate of one-sixtieth a month, or twenty per cent a year.1
The Code of Hammurabi, around 1780 BC, regulates much of this business. It requires witnesses and a written contract for deposits of valuables, and holds a storekeeper liable for losses caused by neglect. It also governs merchants and the agents they sent out with goods and silver: an agent had to account for everything entrusted to him, and profits were usually divided equally. Payment could be made through a banker or by a written draft against a deposit.2
Later, in the Neo-Babylonian period, wealthy business families such as the Egibi lent, traded and accepted deposits, paying their depositors the same twenty per cent they charged borrowers.1
What it made possible: long-distance trade. Babylonian caravans travelled far beyond the borders of the empire, and a single written law, applied across many cities, helped hold that empire together.2
The Templars: money across borders
The Knights Templar, a military religious order founded to protect pilgrims, became one of medieval Europe’s great financial networks. By the 1240s they offered secure deposits, loans, account statements, money transfers and foreign exchange. A traveller could deposit money in one Templar house and draw on it in another.3
Kings and popes used the network. In 1249 revenues collected in Scotland, Ireland and England were routed through Paris to pay creditors in Rome, and Henry III paid the Byzantine emperor through his account in Constantinople.3
What it made possible: the crusades, royal finance and payments across a continent, carried out through one trusted organisation.
Italy: the birth of the banker
Modern banking takes shape in the trading cities of northern Italy between 1000 and 1350, as commerce across the Mediterranean expands.4 The word itself comes from the banco, the bench on which bankers did business; in Venice, the city rented benches on the Rialto to individual bankers.5
Florence: the great companies
In the early fourteenth century the Bardi and Peruzzi of Florence became “the largest merchant-bankers ever seen in medieval Europe”.6 The Peruzzi alone had fifteen branches across Europe and North Africa.4 Both companies lent heavily to Edward III of England during the opening years of the Hundred Years’ War, and both collapsed in the 1340s.6
The Medici Bank, founded by Giovanni di Bicci de’ Medici in 1397, learned from them. Each branch was a separate partnership under a central holding company, so a loss in one city stayed in that city.7 The bank managed papal finances, lent to European royalty and helped finance many of the military campaigns of the fifteenth century. It turned the family’s wealth into political influence.7
The bill of exchange
The Medici and their rivals moved money with bills of exchange: written orders to pay a sum in another currency, in another city, at a later date. The usual term between London and Venice was ninety days. A merchant could pay for wool in England and settle in Italy without shipping a single coin.4
Double-entry bookkeeping
Italian merchants also kept their books “alla Veneziana”, in the Venetian style, recording every transaction twice so that errors showed themselves. The method was in use by about 1300, and in 1494 the Franciscan friar Luca Pacioli published the first printed account of it. The system used throughout the world today is essentially his.8
Genoa and Venice: banks of the city
Genoa took the next step. In 1407 the city’s creditors were organised into the Casa di San Giorgio, which collected specified taxes to pay their interest. Its bank opened in 1408 and has been described as “the first public bank for deposits, transfers and credit, both in Italy and Europe”. Genoese merchant bankers went on to become the main financiers of the Spanish crown.9
Venice founded its first public bank, the Banco della Piazza di Rialto, in 1587. Its purpose was to keep merchants’ deposits safe and make transfers between accounts simple, and it was forbidden to lend the money deposited with it.10 By around 1640 Italy had twenty-one public banks.9
What it made possible: a trading world stretching from the Levant to London, held together by paper rather than silver. Italian credit financed kings, popes and their wars.
Bruges and Antwerp: the exchange
In the fourteenth century Bruges, in today’s Belgium, linked the Italian traders of the Mediterranean with the German merchants of the Hanseatic League. They met in the square before the Ter Buerse inn, run by the Van der Buerse family for five generations. Exchange rates for several cities were published there from 1370. A German traveller wrote in 1495: “There is a square in Bruges where merchants assemble; it is called De Beurs.”11 The word survives today in bourse, beurs and Börse.
As Bruges’s trade moved to Antwerp, the exchange moved with it. The Antwerp Bourse opened in 1531 with a dedication “To the merchants of all nations”, and Antwerp became, for a time, the centre of the international economy.12 Its exchange was the first to keep written records.11
Antwerp’s financiers lent across Europe. The Fugger family of Augsburg, with capital of more than two million gulden, financed the wars of the Habsburg emperors Maximilian I and Charles V, receiving tax farms and royal monopolies in return.4
Thomas Gresham, who had worked in Antwerp in the 1540s, brought the idea home. His Royal Exchange in London, modelled on the Antwerp Bourse, was opened by Elizabeth I in 1571.13
What it made possible: cooperation between merchants of every nation in a single marketplace, and the finance for the Habsburg empire.
Amsterdam: shares, ships and a public bank
After the fall of Antwerp in 1585, trade and talent moved north to Amsterdam.14
The Dutch East India Company
On 20 March 1602 the Dutch East India Company, the VOC, was founded with a charter declaring that “All the residents of these lands may buy shares in this Company”. There was no minimum investment. During the subscription that August, 1,143 investors put in nearly 3.7 million guilders; one of them was a maid earning fifty cents a day, who invested a hundred guilders.15 Shares could be transferred through the company’s bookkeeper, and a market for them grew up on the bridges and squares of Amsterdam. Historians describe it as the world’s first stock exchange.16
The VOC was designed to compete “not only commercially but also militarily”, and its operations in Asia formed part of the Dutch struggle for independence from Spain.15
The Bank of Amsterdam
In 1609 the city founded the Wisselbank, or Exchange Bank. Merchants deposited coins of every kind and received credit in a single, reliable bank money. Payments were settled by transfer between accounts, and payments above a certain sum had to pass through the bank. Its reserves of coin and metal stood close to one hundred per cent of its deposits.14
The bank provided working capital to the VOC from 1615, bridging the gap between a fleet’s departure and the sale of its cargo.17 It gave the Dutch Republic “over a century of stable prices”, and similar banks opened in Middelburg, Delft, Rotterdam and Hamburg.4,14 It closed in 1820, by which time De Nederlandsche Bank had become the Netherlands’ central bank.17
What it made possible: global trade on a new scale, linking the silver of the Americas with the spices of Asia, and a trading network reaching across Asia.17 It also opened company ownership to ordinary people for the first time.
Stockholm and London: notes on paper
In 1661 Stockholms Banco, founded by Johan Palmstruch, issued the first real banknotes in Europe. They were far more convenient than Sweden’s heavy copper coins, and became so popular that the bank issued more than it could redeem.18 In 1668 Sweden founded a state bank in its place, the Riksbank, today the world’s oldest central bank.19
In London, banking grew up among the goldsmiths. By the second half of the seventeenth century they held money and valuables for their customers, lent part of those funds, and issued “promissory notes payable on demand” that customers used to make payments.20 By 1677 London had forty-four goldsmith banks.4
1694: the Bank of England
In 1688 William of Orange, the Dutch prince, took the English throne with his wife Mary, bringing Dutch ideas and Dutch finance with him. Some in London objected to a national bank because “this project came from Holland… since we had too many Dutch things already”.21
William needed money. England was fighting the Nine Years’ War against France, and in 1695 the writer Charles Davenant observed that “the whole Art of War is in a manner reduced to Money”.22 In 1694 Parliament incorporated the Governor and Company of the Bank of England. Its subscribers lent the government £1.2 million at eight per cent, and the Bank issued its own notes.23 It opened on 1 August 1694 in Mercers’ Hall, with seventeen clerks and two gatekeepers. Its charter declared that it existed to “promote the public Good and Benefit of our People”.24
The effect was immediate. The Bank’s loan met more than ninety per cent of the cost of mobilising the fleet for 1695.23 England’s national debt grew from about £3.3 million in 1692 to £34.9 million in 1712.22 Because Parliament now stood behind the debt, investors trusted it, and the government could borrow more, for longer, at lower rates.25
The East India Company also lent to the government in wartime. Over the eighteenth century much of the debt was gathered into the three per cent consol, a perpetual bond that gave the government a steady way to borrow.26
What it made possible: a navy that could be paid year after year, and with it an empire. London took over Amsterdam’s place at the centre of world trade.14 Britain could now borrow on the strength of its future taxes, and fight, trade and expand on a scale its own revenue could not have supported alone.
The Bank of England grows up
Over the next three centuries the Bank turned from the government’s lender into the banker of the whole system.
- 1844: the Bank Charter Act gave the Bank control of new note issue in England and Wales.24
- 1866: when the discount house Overend Gurney failed, the Bank lent about £10 million in a single week to calm the panic. The episode shaped its role as lender of last resort.24,27
- 1931: Britain suspended the gold standard, which had allowed banknotes to be exchanged for gold.24
- 1946: the Bank was nationalised and became publicly owned.24
- 1997: the Bank gained operational independence, with a Monetary Policy Committee setting interest rates to meet the government’s inflation target.28
- 2009: the Bank began quantitative easing, buying £200 billion of government bonds in its first round.28
Today the Bank’s payment system settles around £775 billion on an average day.24
What it made possible: a stable currency and a banking system with a safety net. Bills of exchange discounted in London financed trade at home and abroad.27
Washington: the Federal Reserve
In 1907 the United States had no central bank, and during that year’s financial panic it turned to a private financier, J. P. Morgan, to steady the banks. Congress responded by creating a National Monetary Commission, and on 23 December 1913 President Woodrow Wilson signed the Federal Reserve Act. It created a system of regional Reserve Banks overseen by a Federal Reserve Board.29
The Fed’s reach is now global. During the financial crisis of 2007 to 2009 it lent dollars to other central banks through “swap lines”, from the European Central Bank and the Bank of England to the central banks of Brazil, Mexico, Korea and Singapore. Lending peaked at more than $580 billion in December 2008.30 The dollar remains the world’s main reserve currency, making up 56.7 per cent of official foreign exchange reserves in mid-2026.31
What it made possible: the dollar’s role as the world’s currency, and America’s place at the centre of global finance.
Basel: the bank for central banks
In 1930, at the Hague Conference, Belgium, France, Germany, Italy, Japan and the United Kingdom signed a convention with Switzerland founding the Bank for International Settlements in Basel. It is the oldest international financial institution. Its first task was to manage Germany’s reparation payments after the First World War, and from the start it was asked to promote cooperation between central banks.32
After the Second World War the BIS ran the European Payments Union, which let European countries trade with each other before their currencies became freely exchangeable.32 In 1974 central bank governors created the Basel Committee on Banking Supervision. Its 1988 accord set a common minimum of eight per cent capital against risk-weighted assets, followed by Basel II and Basel III.33
Today the BIS is owned by 63 central banks, representing about ninety-five per cent of world GDP. It describes its purpose as “to support central banks’ pursuit of monetary and financial stability through international cooperation, and to act as a bank for central banks”.34
What it made possible: cooperation among the world’s central banks, and shared rules for banks in every major economy.
Bretton Woods: the IMF
In July 1944, 730 delegates from forty-four nations met at Bretton Woods, New Hampshire, to design the post-war monetary order. The principal architects were John Maynard Keynes for Britain and Harry Dexter White for the United States. Keynes proposed a global clearing union with its own currency, the bancor; the agreed plan was closer to White’s.35
Member currencies were fixed to the dollar, and the dollar to gold at $35 an ounce. The International Monetary Fund would watch over exchange rates and lend to countries short of reserves, and a sister institution, now the World Bank, would finance reconstruction and development.35 On 15 August 1971 President Nixon closed the “gold window”, ending the exchange of dollars for gold, and currencies have floated ever since.36 The IMF’s role turned to surveillance of exchange rates and economic policy.37
The IMF now has 191 member countries and can lend about $1 trillion.38
What it made possible: the rebuilding of Europe and Japan, and the growth of world trade that we now call globalisation.
A timeline of banking
| Date | Place | Development | What it made possible |
|---|---|---|---|
| c. 3000–1750 BC | Sumer and Babylon | Temple and palace credit, deposits, written contracts | Long-distance trade and an empire held together by law |
| 1100s–1300s | Templar houses across Europe | Deposits and transfers across borders | The crusades and royal finance |
| 1300s–1400s | Florence and Venice | Merchant banks, bills of exchange, double-entry bookkeeping | Trade across Europe and the finance of kings and popes |
| 1407 | Genoa | Casa di San Giorgio, a public bank | Funding for the state and, later, the Spanish crown |
| 1300s–1531 | Bruges and Antwerp | The bourse | A marketplace for merchants of all nations |
| 1602–1609 | Amsterdam | Dutch East India Company shares and the Wisselbank | Global trade, the Dutch empire, public share ownership |
| 1661–1668 | Stockholm | First European banknotes; the Riksbank | Paper money and the first central bank |
| 1694 | London | The Bank of England | Long-term national debt, naval power and the British Empire |
| 1913 | Washington | The Federal Reserve | The dollar as the world’s currency |
| 1930 | Basel | Bank for International Settlements | Cooperation between central banks |
| 1944 | Bretton Woods | The IMF and World Bank | Post-war recovery and globalisation |
Conclusion
Each step in this story widens the circle of trust. In Babylon people trusted a temple; in Florence, a family; in Genoa, Venice and Amsterdam, a city; in London, a nation and its Parliament. Today central banks trust one another through institutions in Basel and Washington.
Each widening brings new power. Paper promises let merchants trade across seas, kings raise armies and fleets, companies build empires, and nations rebuild after war. The Bank of England stands at the turning point: it joins the Italian banker, the Dutch investor and the English Parliament, and turns a nation’s future taxes into present strength. The roles it gathered over the following centuries, as issuer of notes, lender of last resort and guardian of the currency, are the roles central banks share today.
- Michael Hudson, “Palatial credit: origins of money and interest” – https://michael-hudson.com/2018/04/palatial-credit-origins-of-money-and-interest/
- Fordham University, Medieval Sourcebook: Code of Hammurabi – https://sourcebooks.web.fordham.edu/ancient/hamcode.asp
- Inner Temple Yearbook, “The Knights Templars: the first City bankers?” – https://publications.innertemple.org.uk/yearbook/articles/2023-2024/the-knights-templars-the-first-c…
- Encyclopedia.com, “Banking and credit” – https://www.encyclopedia.com/history/encyclopedias-almanacs-transcripts-and-maps/banking-and-credit
- Rialto Square, Venice – https://en.wikipedia.org/wiki/Rialto_Square
- Journal of Economic History, “A new look at the dealings of the Bardi and Peruzzi with Edward III” – https://www.cambridge.org/core/journals/journal-of-economic-history/article/abs/new-look-at-the-deal…
- EBSCO Research Starters, “House of Medici” – https://www.ebsco.com/research-starters/history/house-medici
- BBC News, “Is this the most influential work in the history of capitalism?” – https://www.bbc.co.uk/news/business-41582244
- Giuseppe Felloni, “A profile of Genoa’s Casa di San Giorgio (1407–1805)” – https://www.giuseppefelloni.com/rassegnastampa/A%20Profile%20of%20Genoa's%20Casa%20di%20San%20Giorgio.pdf
- “Il Banco della Piazza di Rialto, première banque publique vénitienne”, Persée – https://www.persee.fr/doc/camed_0395-9317_1981_hos_5_1_1552
- National Bank of Belgium Museum, “The origins of the stock exchange: from the Ter Buerse inn to Wall Street” – https://museum.nbb.be/en/resources/origins-stock-exchange-ter-buerse-inn-wall-street
- Pilot Guides, “Antwerp – a history” – https://www.pilotguides.com/articles/antwerp-a-history/
- The Royal Exchange, “Founding” – https://www.royalexchange-grandcafe.co.uk/history/founding/
- New Netherland Institute, “The Amsterdamsche Wisselbank” – https://www.newnetherlandinstitute.org/application/files/2916/8367/0180/Amsterdamsche_Wisselbank.pdf
- Euronews, “How a Dutch trading company started the world’s first stock exchange” (2025) – https://www.euronews.com/2025/04/13/how-a-dutch-trading-company-started-the-worlds-first-stock-exchange
- “The world’s first stock exchange”, University of Amsterdam doctoral thesis – https://pure.uva.nl/ws/files/1427419/85975_14.pdf
- Bank for International Settlements, Working Paper 902, “An early stablecoin? The Bank of Amsterdam” – https://www.bis.org/publ/work902.pdf
- Sveriges Riksbank, “1661 – First banknotes in Europe” – https://www.riksbank.se/en-gb/about-the-riksbank/history/historical-timeline/1600-1699/first-banknot…
- Sveriges Riksbank, “Historical timeline” – https://www.riksbank.se/en-gb/about-the-riksbank/history/historical-timeline/
- Bank of England Quarterly Bulletin, “The Bank of England note: a short history” (1969) – https://www.bankofengland.co.uk/quarterly-bulletin/1969/q2/the-bank-of-england-note---a-short-history
- Bank of England, “The Dutch legacy” (2002) – https://www.bankofengland.co.uk/-/media/boe/files/news/2002/july/go-dutch-at-the-bank-of-england-museum.pdf
- Pepijn Brandon, “‘The whole art of war is reduced to money’”, Financial History Review (2018) – https://www.cambridge.org/core/journals/financial-history-review/article/whole-art-of-war-is-reduced…
- Histoire & Mesure, “Parliament, naval spending and the public” – https://journals.openedition.org/histoiremesure/5209
- Bank of England, “Our history” – https://www.bankofengland.co.uk/about/history
- Douglass North and Barry Weingast, “Constitutions and commitment” (1989) – https://econpapers.repec.org/article/cupjechis/v_3a49_3ay_3a1989_3ai_3a04_3ap_3a803-832_5f00.htm
- NBER, chapter on the East India Company and government finance – https://www.nber.org/system/files/chapters/c13506/revisions/c13506.rev1.pdf
- Yale Program on Financial Stability, “Bank of England lending during the panic of 1866” – https://newbagehot.yale.edu/docs/united-kingdom-bank-england-lending-during-panic-1866
- Bank of England, “Twenty years of Bank of England independence” (2017) – https://www.bankofengland.co.uk/-/media/boe/files/speech/2017/twenty-years-of-boe-independence-the-e…
- Federal Reserve History, “Federal Reserve Act signed into law” – https://www.federalreservehistory.org/essays/federal-reserve-act-signed
- Federal Reserve Bank of New York, “The Federal Reserve’s foreign exchange swap lines” (2010) – https://www.newyorkfed.org/medialibrary/media/research/current_issues/ci16-4.pdf
- IMF, “Currency composition of official foreign exchange reserves”, 30 September 2026 – https://data.imf.org/en/news/imf%20data%20brief%20september%2030
- Bank for International Settlements, “History of the BIS” – https://www.bis.org/about/history/overview
- Basel Committee on Banking Supervision, “History” – https://www.bis.org/committees/bcbs/history
- Bank for International Settlements, “About the BIS” – https://www.bis.org/about/index.htm
- Federal Reserve History, “Creation of the Bretton Woods system” – https://www.federalreservehistory.org/-/media/Project/FedHistory/FedHistory/Documents/essaysPDFs/Cre…
- Federal Reserve History, “Nixon ends convertibility of US dollars to gold” – https://www.federalreservehistory.org/essays/gold-convertibility-ends
- IMF, “From the history books: the rethinking of the international monetary system” (2021) – https://www.imf.org/en/blogs/articles/2021/08/16/from-the-history-books-the-rethinking-of-the-intern…
- IMF, “About the IMF” – https://www.imf.org/en/About